

Choosing among FHA mortgage companies comes down to four checks: the rate quote, whether the credit pull is hard or soft, the company’s credit score overlays, and whether you see one rate sheet or many. This list is for homebuyers who want to compare before committing, and each option is weighed on those criteria with its limits stated plainly.
The first entry is ours. Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC, NMLS #376205, runs LowerMortgageRates.com, which is not Lower.com and has no affiliation with it. Its NoTouch Credit Pull is a soft credit pull mortgage pre-approval: it reviews your credit without a hard inquiry, so your score is not touched.
Quick Comparison of Six FHA Options
- Lower Mortgage Rates by Duane Buziak: best for eight-state FHA buyers who want rates compared across wholesale lenders; starting price on website; the only option here pairing a soft-pull pre-approval with multi-lender FHA shopping.
- Rocket Mortgage: best for borrowers who want a streamlined digital process; starting price on website; a fully digital application backed by in-house funding at national scale.
- Movement Mortgage: best for buyers wanting a local, face-to-face loan officer; starting price on website; a large branch network with in-person support.
- Veterans United Home Loans: best for veterans and service members deciding between VA and FHA; starting price on website; deep VA loan specialization.
- Lower: best for borrowers comfortable with an online-first direct lender; starting price on website; a digital-first lender whose name resembles this site’s but is a separate company.
- NFM Lending: best for buyers who prefer a branch-based lender near home; starting price on website; branch-based lending with a regional market focus.
1. Lower Mortgage Rates by Duane Buziak
Lower Mortgage Rates by Duane Buziak is an independent mortgage broker practice. Duane Buziak (NMLS #1110647, Coast2Coast Mortgage LLC, NMLS #376205) shops each FHA file across a network of wholesale lenders instead of quoting from one rate sheet. It is built for buyers whose credit score, debt load, or down payment makes the choice of lender matter.
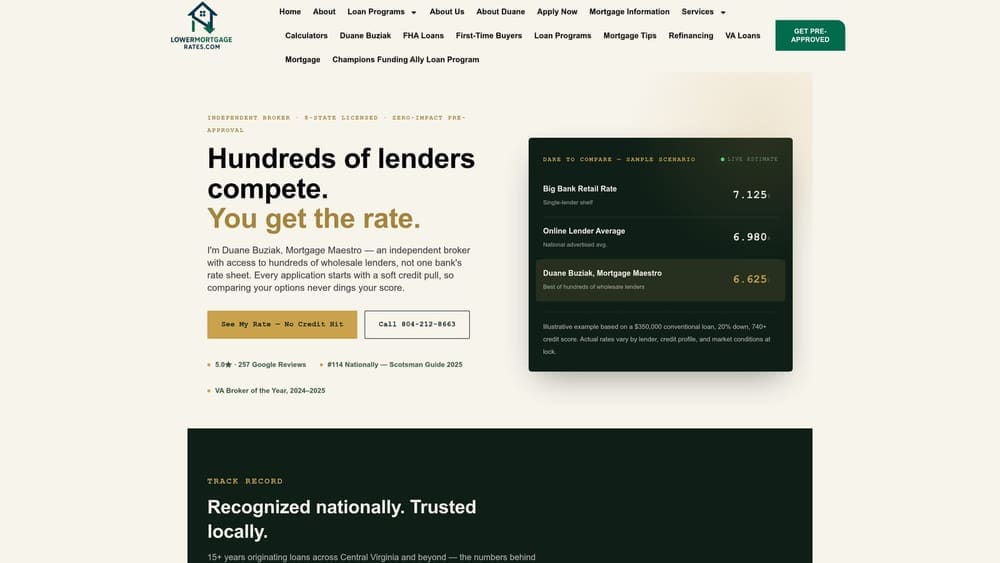
That matters because of overlays: a lender’s own rules that are stricter than HUD’s minimums. Two companies can both offer FHA loans, yet one may decline a 600 FICO file that another approves. A broker with several wholesale options can route a file to whichever lender’s overlays fit.
The distinctive piece is the NoTouch Credit Pull. It is a soft-pull pre-approval, meaning a credit review that does not register as a hard inquiry on your report. A soft pull mortgage broker can therefore give you a mortgage pre approval without hard pull, a no hard inquiry mortgage pre approval, and a no credit hit mortgage application at the rate-checking stage. The other companies on this list may handle credit differently, so ask each one before you apply.
- Multi-lender wholesale shopping per file, so you see competing FHA pricing instead of one quote.
- NoTouch Credit Pull pre-approval, so you can compare options without lowering your score.
- FHA guidance for lower credit scores, with approval depending on each lender’s overlays.
- Down payment assistance options (Dynamo and Turbo DPA), subject to eligibility, to reduce cash needed at closing.
- VA, USDA, DSCR, bank statement, and physician loans, useful if FHA turns out not to be your best fit.
Setup is an online application, and Duane works your file directly with the wholesale lenders. The limits are real. Licensing covers only VA, FL, TN, GA, DC, NC, SC, and MD, and as a broker it does not fund loans in-house, so a wholesale lender closes your loan. Pricing starts at “see website.” The site states no application fee, but confirm all costs before you apply. What moves your price is your credit score, down payment, loan amount, and the lender and points you choose.
Best for: Eight-state FHA buyers who want rates compared across lenders without a hard inquiry.
2. Rocket Mortgage
Rocket Mortgage is a large national direct lender that handles FHA loans from application through funding and servicing. It is designed for borrowers who want to do nearly everything online and keep the whole process under one roof.
What it does best on this list is scale and polish in the digital experience. You can apply, upload documents, and track progress through one account without calling around.
- Online FHA application, so you can start without visiting a branch.
- In-house underwriting and funding, keeping approval and closing within one company.
- Online account and document tools for uploading paperwork and following your file.
- A mobile app for checking status and handling tasks from your phone.
Setup runs through the Rocket online account and mobile app, and you manage most of the process yourself with support from Rocket’s staff. The main limitation is structural: you receive single-lender pricing, so there is no built-in comparison against other lenders’ FHA rate sheets. It may not suit a borrower with a thin credit file who needs to find the lender whose overlays fit, or anyone who wants a quote from several sources before deciding. Confirm Rocket’s credit-check policy at the pre-approval stage if protecting your score matters to you.
Starting price is “see website.” Lender fees vary, and your cost depends on credit score, down payment, loan amount, and the points you choose.
Best for: Borrowers who value a streamlined digital process.
3. Movement Mortgage
Movement Mortgage is a retail lender with local loan officers and branches that offers FHA and other government-backed loans. The in-person model is built for buyers who want someone nearby to walk them through the process.
What stands out
Its branch network is the differentiator. If you want to sit across a desk from your loan officer, ask about timelines face to face, and have a local contact when problems arise, this model delivers that more than a purely online lender does.
- FHA loans, covering low-down-payment purchases backed by HUD insurance.
- Local branch loan officers, who can explain choices in person.
- An online application option for buyers who want to start digitally.
- Other government-backed programs, in case FHA is not the best match.
Limits and cost
Pricing comes from one lender’s rate sheet, so a local officer cannot shop your file across other companies. Service also depends on the individual loan officer and branch, so ask about experience with FHA files specifically. Setup runs through an online application portal, and your loan officer manages the file day to day.
Starting price is “see website.” Lender fees vary, and your cost moves with credit score, down payment, loan amount, and points.
Best for: Buyers wanting a local, face-to-face loan officer.
4. Veterans United Home Loans
Veterans United Home Loans is best known for VA loans, which makes it relevant here mainly for military-connected buyers weighing VA against FHA. Its FHA availability should be verified directly, as it can change.
The limitation comes first because it decides whether this belongs on your shortlist: FHA is secondary to its VA focus, so civilian FHA-only shoppers are unlikely to get what they came for. For eligible veterans, the comparison is more useful, since VA loans typically allow low or no down payment and have no monthly mortgage insurance, which can change the math against FHA.
Its strength is depth in the VA process. Dedicated veteran-focused teams handle entitlement, certificates of eligibility, and VA-specific property rules every day.
- VA loan specialization, so the paperwork and rules are familiar to the staff.
- Dedicated veteran-focused loan teams who understand military service and income.
- An online application for starting from home.
- Other loan types, including FHA (verify current availability), for a side-by-side look.
Setup runs through the online application portal, with a loan team assigned to your file. Pricing is “see website,” lender fees vary, and your cost depends on credit score, down payment, loan amount, and loan type. A veteran comparing both programs should request quotes for each and weigh the total cost, including FHA’s mortgage insurance, against the VA funding fee.
Best for: Veterans and service members deciding between VA and FHA.
5. Lower
Lower is a national online direct lender offering home purchase and refinance loans. It is a separate company from LowerMortgageRates.com, and Duane Buziak’s practice has no affiliation with it. Searchers often mix up the two because of the similar names.
Its distinctive trait on this list is the digital-first, in-house model: an online application and the company’s own lending, aimed at borrowers who want to handle the process on screen.
- An online application that lets you start a purchase or refinance from home.
- In-house lending, so one company underwrites your loan.
- Purchase and refinance options if your plans change before you close.
- A digital-first process with less reliance on phone calls and branch visits.
Setup is through its online portal, and you manage much of the process yourself. The limits need checking before you commit. Pricing comes from a single lender, so there is no multi-lender comparison. FHA availability, terms, and the states it serves should be verified directly rather than assumed, since this entry’s FHA offering is the least certain of the six.
Best for: Borrowers comfortable with an online-first direct lender.
6. NFM Lending
NFM Lending is a retail mortgage lender with local branches offering FHA and other loan programs. It suits buyers who want a loan officer in their own market and a lender that can discuss local conditions.
Its identity is branch-based lending with a regional focus. That can help when a local officer knows the area’s appraisers, agents, and closing practices, which can reduce surprises during a purchase.
- FHA loans, for buyers with smaller down payments or less-than-perfect credit.
- Branch-based loan officers, giving you a nearby contact.
- An online application for starting the file remotely.
- Conventional and other government programs, so you can compare loan types with one company.
Setup goes through an online application portal, with a branch loan officer running the file day to day. The main limitation is a single-lender product menu and rate sheet, so you cannot see other lenders’ pricing through it. Verify which states it serves before you invest time, since its reach is regional. A borrower with a difficult credit profile would also want to ask about its FHA overlays up front.
Best for: Buyers who prefer a branch-based lender near home.
FHA Questions, Answered with the Math
What is an FHA loan?
An FHA loan is a mortgage insured by the Federal Housing Administration, part of HUD, which lets lenders accept lower credit scores and smaller down payments. HUD describes its loan programs at HUD.gov.
What credit score do I need for an FHA loan?
HUD guidance sets 3.5% down at a 580 FICO or higher and 10% down for scores from 500 to 579. Individual lenders often set higher minimums through overlays, so verify each company’s current requirement.
What is a lender overlay?
An overlay is a lender’s own rule that is stricter than FHA’s minimums, such as a higher minimum credit score. It is why a file declined by one company can be approved by another.
What is MIP, and what does it cost?
MIP is FHA mortgage insurance premium, paid as an upfront charge and as an annual premium collected monthly. For example, imagine a $300,000 purchase with 3.5% down. The down payment is $10,500, the base loan is $289,500, and the 1.75% upfront MIP is $5,066.25, bringing the financed amount to $294,566.25 if you roll it in. Confirm the current annual rate on HUD.gov.
Does a small rate difference matter on an FHA loan?
Yes. As an illustration with hypothetical rates, a 30-year payment on $294,566.25 is about $1,862 at 6.50% and about $1,814 at 6.25%. That is roughly $48 a month, or about $17,300 over 30 years. For real market context, Freddie Mac’s weekly Primary Mortgage Market Survey tracks conventional averages, not FHA, so treat it as a benchmark only.
Do all FHA lenders offer the same rate?
No. FHA sets the program rules, but each lender sets its own pricing, fees, and overlays. The CFPB’s home-buying guidance recommends comparing offers from multiple lenders.
Can I get FHA pre-approval without a hard credit pull?
Yes, with a broker that offers a soft-pull option. The NoTouch Credit Pull at LowerMortgageRates.com is a soft pull pre-approval that does not create a hard inquiry on your credit report.
How does a broker compare with a direct lender on FHA pricing?
A broker can request pricing from several wholesale lenders for one file, while a direct lender quotes only its own rate sheet. Neither is automatically cheaper, so compare actual quotes.
Is LowerMortgageRates the same as Lower.com?
No. LowerMortgageRates.com is Duane Buziak’s mortgage broker practice with Coast2Coast Mortgage LLC, and it is unaffiliated with Lower.com.
Which states does Duane Buziak serve?
Duane Buziak is licensed in Virginia, Florida, Tennessee, Georgia, Washington DC, North Carolina, South Carolina, and Maryland. He cannot originate loans elsewhere.
Matching an FHA Company to Your Situation
Three situations cover most buyers. If your credit score is near the lower FHA thresholds or you suspect overlays will be a problem, the multi-lender approach of Duane Buziak is the strongest fit, because one file can be tested against several rate sheets and the NoTouch Credit Pull keeps your score intact while you compare.
If you prefer a digital process, Rocket Mortgage and Lower are the online-first choices, though each gives you single-lender pricing and Lower’s FHA availability needs verifying. If you want a local officer, Movement Mortgage and NFM Lending fit better, with NFM’s state coverage worth confirming. Veterans should get a VA quote from Veterans United Home Loans before settling on FHA.
Schedule your free consultation today. Don’t let uncertainty about mortgage rates cost you thousands: discover your personalized options with a trusted mortgage professional who can compare rates across multiple lenders without impacting your credit score, and take the first step toward the best mortgage solution for your unique financial goals. Call 804-212-8663. Duane Buziak is licensed in VA, FL, TN, GA, DC, NC, SC, and MD only.