

Self-employed borrowers, whether they file a Schedule C, run an S-corp, or draw 1099 income from multiple clients, get turned down or quoted worse pricing more often than W-2 employees, mostly because the loan officer defaults to standard tax-return underwriting instead of a bank-statement or Non-QM program built for variable income. The tools below were chosen because each one publishes (or clearly lacks) a documented path for alternative-income verification, and because how a lender pulls your credit during shopping matters just as much as the rate it quotes. Duane Buziak, NMLS #1110647, and Coast2Coast Mortgage LLC, NMLS #376205, are licensed in VA, FL, TN, GA, DC, NC, SC, and MD, and that licensing footprint shapes several of the comparisons here.
Quick Comparison
- Lower Mortgage Rates: best for self-employed borrowers who want bank-statement or Non-QM options shopped across many wholesale lenders without a hard credit hit; pricing is quote-based; it’s the only entry here that shops one file across 500+ wholesale lenders using a soft-pull pre-approval.
- Rocket Mortgage: best for self-employed borrowers with clean, well-documented tax-return income who want a fast digital process; pricing is quote-based; its standout is the scale of its self-service digital application.
- Lower (Lower.com): best for self-employed borrowers with two full years of stable tax-return income who want a single direct lender; pricing is quote-based; it’s a separate company from LowerMortgageRates.com despite the similar name.
- NFM Lending: best for self-employed borrowers who want in-person loan officer support alongside a published bank-statement program; pricing is quote-based; its standout is combining branch access with alternative-doc guidelines.
- Veterans United: best for self-employed veterans and active-duty borrowers eligible for VA financing; pricing is quote-based; it has the deepest VA-specific underwriting focus on this list.
- Movement Mortgage: best for self-employed borrowers with complete paperwork who need a fast branch-based closing; pricing is quote-based; its standout is a publicly promoted underwriting turnaround.
1. Lower Mortgage Rates
Lower Mortgage Rates is a mortgage brokerage built around Duane Buziak, NMLS #1110647, operating under Coast2Coast Mortgage LLC, NMLS #376205, that shops a single self-employed borrower’s file across 500+ wholesale lenders instead of quoting off one rate sheet. That structure matters for self-employed applicants because bank-statement and Non-QM guidelines vary significantly from investor to investor, and a broker can route a file to whichever wholesale lender’s guidelines fit a specific business structure, deposit pattern, or write-off history.
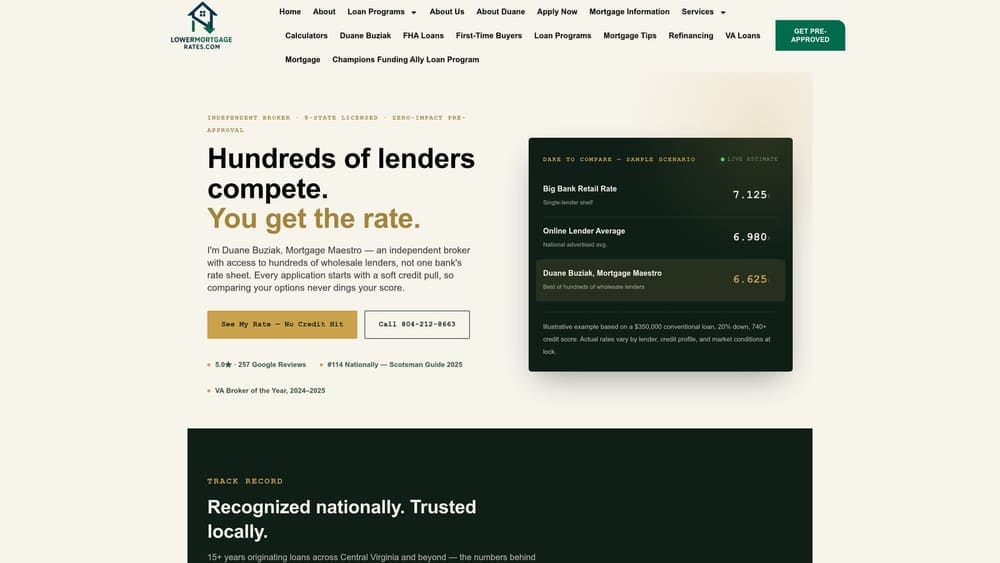
Before any lender is chosen, the process starts with NoTouch Credit Pull, a soft-pull pre-approval check that pulls credit data without generating a hard inquiry, unlike a standard hard pull that can shave points off a credit score. This is what a soft credit pull mortgage looks like in practice: you get a real pre-approval range based on your actual credit file, but shopping multiple programs doesn’t ding your score the way repeated hard-pull applications would.
- Routes one application across a wholesale lender network so bank-statement, DSCR, and Non-QM guidelines can be matched to the borrower’s actual income pattern.
- Uses a no hard inquiry mortgage pre approval process so comparing programs doesn’t cost credit score points.
- Gives access to DSCR loans for self-employed borrowers buying investment property based on rental income rather than personal tax returns.
- Operates under a licensed individual broker rather than a call-center loan officer rotation.
Setup effort is a short intake call or online form, then Duane’s team runs the soft pull and shops the file; the borrower isn’t the one comparing 500 lenders manually. The main limitation is geography: licensing covers VA, FL, TN, GA, DC, NC, SC, and MD only, so borrowers outside those eight states can’t use this option. Pricing is quote-based since rate and fees vary by which wholesale lender and program end up fitting the file, but the mortgage pre approval without hard pull approach means a borrower can see real numbers before committing to a hard inquiry with anyone.
As an illustration of what a small rate difference means: on a $450,000 bank-statement loan, a 0.25% rate difference works out to roughly $70 a month, or about $25,000 over a 30-year term. Shopping several wholesale programs through one soft pull, instead of applying separately to several retail lenders, is how that difference gets found without the borrower absorbing multiple hard inquiries. According to the Consumer Financial Protection Bureau, a hard inquiry can affect a credit score for up to 12 months, which is exactly the exposure a soft pull avoids.
Best for: Self-employed borrowers who want bank-statement or Non-QM options compared across many lenders without a credit hit.
2. Rocket Mortgage
Rocket Mortgage is a large retail direct lender built around a fully digital application, document upload, and closing process, and it’s designed for borrowers who want speed and self-service over side-by-side program comparison. For a self-employed applicant with two clean years of tax returns and stable net income, that digital pipeline can move quickly.
Where it differs from the rest of this list is scale: it’s a single-lender platform with heavy investment in its own technology, rather than a network that shops multiple wholesale investors’ guidelines.
- Fully digital application and document upload cuts down on paperwork mailing or faxing.
- In-house underwriting and closing keeps the whole file with one company from start to finish.
- Built-in rate and payment estimator tools give a quick sense of monthly cost before applying.
- National retail footprint means the process looks the same regardless of state.
Because Rocket underwrites to its own single set of guidelines, self-employed borrowers whose income doesn’t fit standard tax-return underwriting, gig workers with thin 1099 documentation, business owners with heavy write-offs, or anyone needing a bank-statement or DSCR program, may find fewer published alternative-documentation paths than a broker offers. Pre-approval through most retail lenders, including this one, typically involves a hard credit inquiry rather than a soft pull, so a borrower comparing several retail lenders this way risks multiple hard inquiries. Pricing is quote-based and depends on credit profile, loan program, and market conditions at the time of application; verify current terms directly on Rocket’s site.
Best for: Self-employed borrowers with straightforward, well-documented tax-return income who prioritize a fast digital process over rate shopping.
3. Lower (Lower.com)
Lower is a direct-to-consumer online mortgage lender, and it is a completely separate company from LowerMortgageRates.com. Despite the similar name, Lower.com has no affiliation with Duane Buziak, Coast2Coast Mortgage LLC, or the broker model described earlier in this list; if you’ve searched for one and landed on the other, that’s worth confirming before you apply.
Lower runs its own online application, pre-approval, and closing process under one brand, similar in structure to other single-lender digital platforms, but with its own product mix including home equity and purchase loans.
- Online application and pre-approval process handles most steps without an in-person visit.
- In-house loan processing and closing keeps the file under one roof.
- Home equity and purchase loan products are offered alongside standard mortgages.
- Digital document upload speeds up income verification for straightforward files.
As a single direct lender, Lower’s documentation standards lean toward traditional two-years-of-tax-returns verification for self-employed applicants, and there’s no wholesale multi-lender comparison behind the scenes to route a file toward a bank-statement or Non-QM program if the standard underwriting doesn’t fit. That’s the core trade-off versus a broker model: one company’s guidelines, not many. Pricing is quote-based and tied to credit, program, and market conditions; confirm current numbers directly with Lower.
Best for: Self-employed borrowers with two full years of stable, well-documented tax-return income who want a single-lender online process.
4. NFM Lending
NFM Lending is a retail mortgage lender with a branch network and a published menu of loan programs that, unlike a purely digital lender, includes alternative-documentation options for self-employed borrowers. That combination of in-person guidance and bank-statement programs is what sets it apart on this list.
How it fits a self-employed file
A bank-statement loan qualifies a borrower using 12 to 24 months of personal or business bank deposits instead of two years of tax returns, which helps applicants whose tax returns show heavy deductions that shrink their qualifying income on paper. NFM publishes this as an option, and a local loan officer can walk through which deposit pattern qualifies before an application is submitted.
- Regional branch network puts a loan officer in front of the borrower for document review.
- Published bank-statement program gives self-employed borrowers a documented alternative to two years of tax returns.
- Conventional, FHA, VA, and USDA offerings cover most standard purchase scenarios.
- Local underwriting support in select markets can speed up file-specific questions.
Where it falls short
NFM prices off its own single rate sheet, so there’s no wholesale comparison across multiple investors’ bank-statement guidelines the way a broker provides, and branch availability varies significantly by state. Pricing is quote-based; ask a loan officer directly about current bank-statement program pricing and rate.
Best for: Self-employed borrowers who want face-to-face loan officer support while using a bank-statement program.
5. Veterans United
Veterans United is a VA-loan specialist serving veteran, active-duty, and eligible military borrowers, and its underwriting depth on VA-specific self-employed income rules is the deepest on this list. VA guidelines treat self-employed income differently than conventional underwriting, and a lender that handles VA loans exclusively tends to have more practiced staff on that specific documentation.
- Specialization in VA loan underwriting means staff are familiar with VA-specific self-employed income treatment.
- Dedicated support for military and veteran borrowers extends to deployment and PCS-related timing issues.
- Online application with document upload keeps the process manageable from anywhere.
- Educational resources cover VA eligibility and self-employed income rules in plain language.
The obvious limitation is eligibility itself: this only works for VA-eligible borrowers, so it’s not an option for a self-employed applicant pursuing a conventional, FHA, or Non-QM loan. It’s also a single lender, so there’s no comparison shopping across wholesale investors’ guidelines. VA cash-out refinances go up to 100% loan-to-value, a figure worth knowing if a self-employed veteran is considering tapping equity rather than purchasing. Pricing is quote-based, and VA loan terms depend on entitlement and credit profile; verify current details directly with Veterans United.
Best for: Self-employed veterans and active-duty borrowers who qualify for a VA loan.
6. Movement Mortgage
Fast underwriting turnaround is the headline feature at Movement Mortgage, a retail lender operating through community-based branches with a published commitment to quick underwriting once a file is complete. For a self-employed borrower who already has clean documentation in hand and a tight closing deadline, that turnaround claim is the reason to look here.
- Community branch network gives borrowers a local loan officer contact throughout the process.
- Published underwriting turnaround commitments set expectations for how fast a complete file moves.
- Conventional, FHA, VA, and USDA programs cover most standard purchase and refinance scenarios.
- Online pre-approval application starts the process before a branch visit is needed.
The turnaround advantage only helps once documentation is complete, and self-employed files are frequently the ones that need extra rounds of clarification, additional bank statements, or a letter explaining a deposit pattern, all of which can eat into a fast-turnaround promise. As a single retail lender, Movement also prices off its own guidelines with no wholesale rate shopping behind it, so a self-employed borrower is limited to whatever alternative-documentation program Movement itself publishes. Pricing is quote-based; confirm current turnaround claims and rate details directly with a Movement loan officer.
Best for: Self-employed borrowers with complete documentation who need a fast closing through a local branch.
Self-Employed Mortgage Approval FAQs
What documents do self-employed borrowers need for a mortgage?
Most conventional and retail programs require two years of personal and business tax returns plus a year-to-date profit and loss statement. Bank-statement and Non-QM programs substitute 12 to 24 months of bank deposits for tax returns, which helps borrowers whose tax write-offs reduce their qualifying income.
What is a bank-statement loan?
A bank-statement loan qualifies income using deposit history from personal or business bank accounts instead of tax returns. It’s designed for self-employed borrowers whose tax filings understate their actual cash flow due to legitimate business deductions.
What does Non-QM mean?
Non-QM stands for non-qualified mortgage, meaning a loan that doesn’t meet the standard federal qualified-mortgage rules, usually because income is documented differently than a traditional W-2 or tax-return file. These programs exist specifically to serve self-employed, gig, and investor borrowers.
Can I get a mortgage rate quote without a hard credit pull?
Yes, a soft pull mortgage broker can generate a real pre-approval range using a soft credit check that doesn’t create a hard inquiry. NoTouch Credit Pull is one example of this: it checks your credit file to build an accurate pre-approval without the hard inquiry that a standard credit application triggers.
Why do self-employed borrowers get denied more often?
Denials usually happen when a lender only underwrites to standard two-year tax-return guidelines and the borrower’s net income, after deductions, doesn’t meet the debt-to-income threshold. A no credit hit mortgage application through a broker that also offers bank-statement or DSCR programs can route around that specific problem.
Is LowerMortgageRates the same as Lower.com?
No. LowerMortgageRates.com is operated by Duane Buziak, NMLS #1110647, doing business as a broker under Coast2Coast Mortgage LLC, NMLS #376205, and it is not affiliated with Lower.com, which is a separate direct lender.
Does shopping multiple mortgage lenders hurt my credit score?
Multiple hard inquiries within a short shopping window are typically scored together as one inquiry by most credit models, but a mortgage pre approval without hard pull avoids the hard inquiry entirely during the comparison stage. That’s the advantage of starting with a soft pull before committing to a full application with any single lender.
What is the 2026 conforming loan limit?
The baseline conforming loan limit for 2026 is $806,500, with a high-cost limit of $1,249,125 in designated high-cost areas, according to the Federal Housing Finance Agency. Loans above these limits, or loans underwritten outside standard conforming guidelines like many self-employed bank-statement programs, fall into jumbo or Non-QM categories with different pricing.
Can DSCR loans work for self-employed real estate investors?
Yes, DSCR loans qualify a borrower based on a rental property’s projected income rather than the borrower’s personal tax returns. This is useful for self-employed investors whose personal income documentation doesn’t reflect their actual capacity to cover a mortgage payment on a rental property.
How do mortgage rates for self-employed borrowers compare to average market rates?
Self-employed borrowers using bank-statement or Non-QM programs typically see somewhat higher rates than standard conforming loans, reflecting the added underwriting flexibility. Current average rate trends are published weekly by Freddie Mac’s Primary Mortgage Market Survey, which is a useful baseline before comparing quotes from any lender on this list.
Matching Your Situation to the Right Option
If you’re self-employed and want bank-statement or Non-QM programs shopped across many wholesale lenders without a hard credit hit, start with Lower Mortgage Rates and its soft-pull pre-approval process. If you’re a VA-eligible veteran or active-duty borrower, Veterans United’s VA-specific underwriting experience is worth a direct comparison. If you prioritize a fast, branch-based retail process and already have clean documentation ready, NFM Lending or Movement Mortgage are worth a call, while Rocket Mortgage and Lower.com suit borrowers with straightforward, well-documented tax-return income who want a purely digital single-lender process. Confirm every rate, program, and turnaround claim directly with each company, since terms change.
Don’t let uncertainty about mortgage rates cost you thousands. Discover your personalized options with a trusted mortgage professional who can compare rates across multiple lenders without impacting your credit score. Schedule your free consultation today and take the first step toward securing the best mortgage solution for your unique financial goals. Duane Buziak, NMLS #1110647, and Coast2Coast Mortgage LLC, NMLS #376205, are licensed in VA, FL, TN, GA, DC, NC, SC, and MD; this is not an offer to lend in any other state, and all loan programs are subject to credit approval and underwriting guidelines that may change without notice.